Every Home Has a Story. The Next Chapter Begins When You're Ready.For many homeowners, selling the family home is one of the most emotional decisions they'll ever make.This isn't just a piece of

Dated: December 30 2022
Views: 89
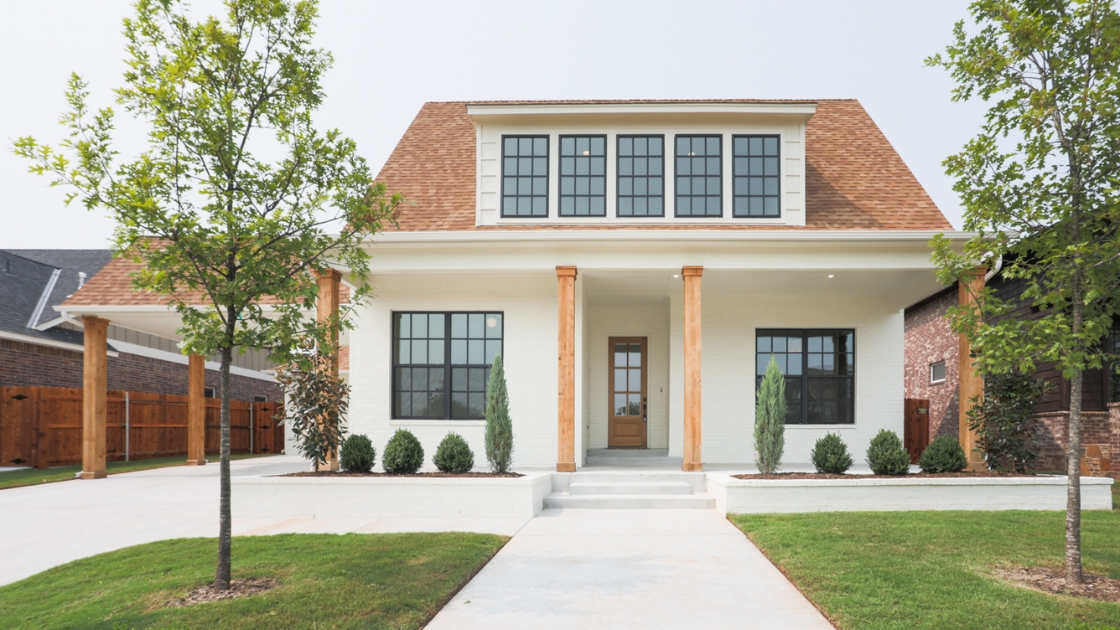
Home equity…Everybody wants it, but what exactly is it, and how do you get it?
Equity represents the degree of ownership an individual or entity has in an asset after subtracting any debts against the asset. To say someone shares equity in a company means they would share in any assets remaining after all debts are accounted for.
For example, if your business has sold $500,000 worth of product this year, but you have rent, operating expenses, and a business loan payment totaling $400,000 for the year, you have $100,000 of equity in your business. Equity changes as the value of your assets and debts change.
Home equity works the same way. When you take out a mortgage to purchase a home, your home is collateral on the mortgage loan, so the outstanding mortgage principal must be deducted from the value of the home to determine your home equity.
In most cases, you make a down payment when you purchase your home. That down payment is your initial home equity. If you pay a 20% down payment on a $200,000 home, you have $40,000 equity when you close on your purchase.
As time goes on, and you continue to pay down your mortgage principal, your equity grows. Usually, the longer you own your home, the more equity you gain because you are paying down your mortgage. However, any debts you take on using your home value as collateral, such as a second mortgage or home equity line of credit (HELOC) decrease your home equity.
The changing real estate market also influences your equity. If you paid $200,000 for your home, and two years later the homes in your neighborhood start selling in the $400,000 range, your theoretical equity increases. (Theoretical because you don’t realize your home equity until you sell your home and pay off all debts against it.) You can also lose equity if the market takes a dive, but be patient, and it should recover in time.
Equity also grows if you make improvements on your home that increase its value. Let’s say you add a swimming pool and all new appliances. You have increased the value of the home. Your equity doesn’t increase by the amount you spent on the improvements, but on the value you get upon resale. This is an important point when considering making improvements prior to putting your home on the market, and one that is often misunderstood.
Let’s say Joe spends $50,000 on upgrades to his home. He might tell his neighbor, “I have $50,000 in my home,” but when he goes to sell, the current market dictates how much he will actually get in return. If Joe ends up selling for $40,000 more than he originally paid, his $50,000 investment got him $40,000 in home equity.
Some things you can do to increase your home equity include:
1) Make a large down payment when you purchase your home. The more cash you put down, the more equity you begin with.
2) Make increased or extra payments on your mortgage principal. Adding to the principal portion only on your monthly payments, or making extra payments when you are able, helps chip away at your outstanding debt.
3) Be smart when making home improvements. Not all improvements build equity. Some improvements may be personal preferences that don’t necessarily add value for resale. Improvements such as a new HVAC system, new appliances, or a new roof are usually more reliable investments than a fountain in the front yard or surround sound speakers throughout the house.
4) Don’t borrow against your home equity unless you must. Home equity is often a homeowner’s biggest asset, and can help to build your retirement nest egg, but it can also come in handy if life throws you a curveball, and you need to borrow against it for an unforeseen emergency. Be careful not to borrow against your equity for frivolous purposes, so it will be there if you really need it.
5) Sell when the market is favorable. If you are counting on your home equity to help finance your next home, pay for your children’s education, or add to your retirement funds, try to sell during a seller’s market when inventory is needed in your area.

Mike Conner is a trusted Realtor serving Aurora and the surrounding Colorado communities, with a special focus on Seniors 55+ and Move-Up Buyers navigating life’s next chapter. With years of exp....
Every Home Has a Story. The Next Chapter Begins When You're Ready.For many homeowners, selling the family home is one of the most emotional decisions they'll ever make.This isn't just a piece of
Don't Just Buy Your Next House—Choose the Home That Fits Your FutureBuying a home in your 30s or 40s often revolves around growing a family.You need more bedrooms.A larger yard.Better schools
The smartest improvement isn't always the biggest one. It's the one that helps you sell without spending money you'll never get back.If you've lived in your home for 20 or 30 years, chances are you
Downsizing can create freedom—but the wrong decisions can cost you thousands.For many Empty Nesters, downsizing sounds simple:Sell the big house. Buy something smaller. Keep the difference.But
 The content relating to real estate for sale in this Web site comes in part from the Internet Data eXchange (IDX) program of METROLIST, INC., DBA RECOLORADO©. Real estate listings held by brokers other than EXIT Realty, A Smart Move are marked with the IDX Logo. This information is being provided for the consumers' personal, non-commercial use and may not be used for any other purpose. All information subject to change and should be independently verified. September 26, 2026 11:19 AM UTCd
1. This publication is designed to provide information regarding the subject matter covered. It is displayed with the understanding that the publisher and authors are not engaged in rendering real estate, legal, accounting, tax, or other professional services and that the publisher and authors are not offering such advice in this publication. If real estate, legal, or other expert assistance is required, the services of a competent, professional person should be sought.
2. The information contained in this publication is subject to change without notice.
METROLIST, INC., DBA RECOLORADO MAKES NO WARRANTY OF ANY KIND WITH REGARD TO THIS MATERIAL, INCLUDING, BUT NOT LIMITED TO, THE IMPLIED WARRANTIES OF MERCHANTABILITY AND FITNESS FOR A PARTICULAR PURPOSE. METROLIST, INC., DBA RECOLORADO SHALL NOT BE LIABLE FOR ERRORS CONTAINED HEREIN OR FOR ANY DAMAGES IN CONNECTION WITH THE FURNISHING, PERFORMANCE, OR USE OF THIS MATERIAL.
3. PUBLISHER'S NOTICE:
All real estate advertised herein is subject to the Federal Fair Housing Act and the Colorado Fair Housing Act, which Acts make it illegal to make or publish any advertisement that indicates any preference, limitation, or discrimination based on race, color, religion, sex, handicap, familial status, or national origin.
4. METROLIST, INC., DBA RECOLORADO will not knowingly accept any advertising for real estate that is in violation of the law. All persons are hereby informed that all dwellings advertised are available on an equal opportunity basis.
5. 
6. © 2026 METROLIST, INC., DBA RECOLORADO© - All Rights Reserved
6455 S. Yosemite St., Suite 500
Greenwood Village, CO 80111 USA
7. ALL RIGHTS RESERVED WORLDWIDE. No part of this publication may be reproduced, adapted, translated, stored in a retrieval system or transmitted in any form or by any means, electronic, mechanical, photocopying, recording, or otherwise, without the prior written permission of the publisher. The information contained herein including but not limited to all text, photographs, digital images, virtual tours, may be seeded and monitored for protection and tracking.
Options
Show More...
